You’re about to tap “Buy”—what’s actually happening behind the scenes?
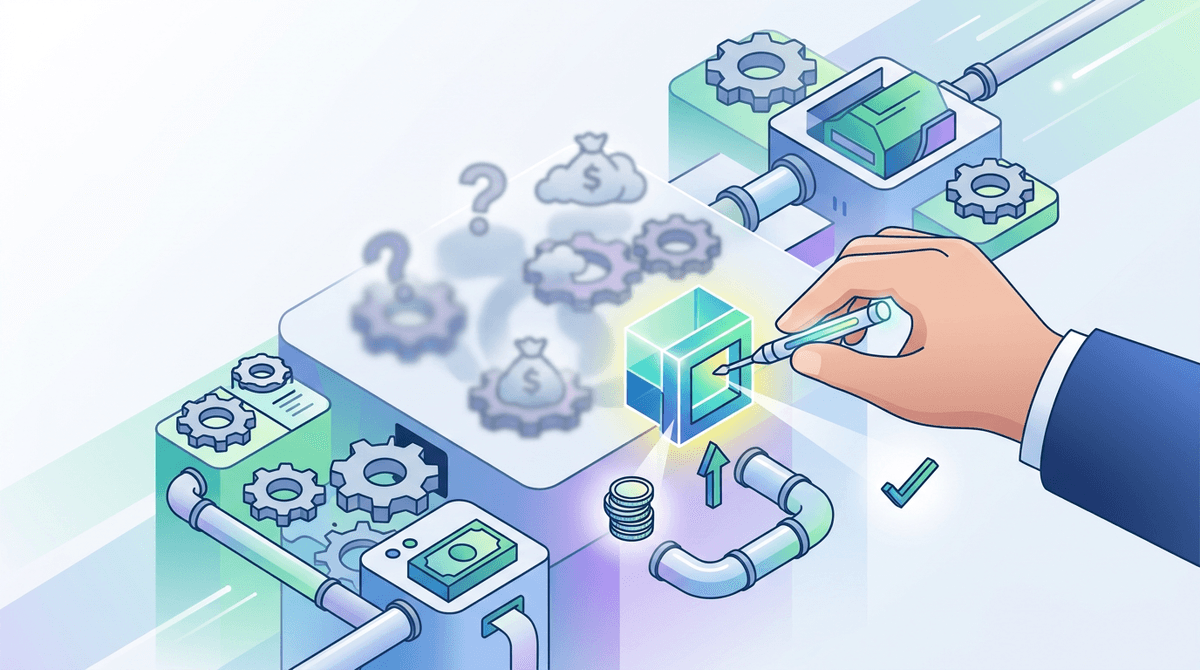
You open a brokerage app, type a company name, and a big “Buy” button makes it feel instant. But your tap actually creates an order: instructions your broker routes to a market venue, matched with someone willing to sell, then “settled” so shares and cash officially exchange hands.
That gap is where surprises live. Prices can change between the quote you see and the fill you get, transfers can take days, and some apps make money through order routing—usually not a direct fee, but it can affect execution.
Before you ever place an order, the safest win is picking a broker that’s straightforward about costs, fills, and account protections.
Picking a brokerage app without stepping into obvious traps
That “straightforward about costs, fills, and account protections” line sounds simple until you’re staring at five apps that all promise “commission-free” trading. The quick filter is basic legitimacy: the broker should be registered with the SEC, belong to FINRA, and carry SIPC coverage. Those aren’t perks; they’re table stakes that help if the firm fails, not if your stock drops.
Then look for the traps hiding behind “free.” If an app earns money from order routing, you want clear execution disclosures and an easy-to-find price improvement report. If it pushes margin, options, or crypto hard, expect more prompts and more ways to click into risk.
One real-world annoyance: support and transfers. When a deposit gets held or an account is locked for verification, fast chat replies matter more than a slick chart—especially right before you plan to fund and buy.
Which account should you open if you just want to buy one stock?
That same moment where verification can lock you out is also when most people pick an account type too fast, then have to fix it later. If your goal is simply to buy one stock in the next few days, a standard individual taxable brokerage account is usually the cleanest start: it’s flexible, easy to fund, and you can sell whenever you want.
A retirement account like a Roth IRA can be great, but it adds rules you’ll feel immediately. You may need extra setup steps, contribution limits apply, and pulling money back out can get complicated if you treat it like a regular spending account.
One practical constraint: account “approval” isn’t always instant. Identity checks, name mismatches with your bank, or joint-account details can delay funding, so open the simplest account you’ll actually use before you start hunting for the ticker.
Funding the account: the moment fees and delays surprise beginners
That “approval isn’t always instant” warning tends to show up again when you try to add money. Most apps offer a few funding paths: an ACH bank transfer, a wire, a debit card, or a mailed check. ACH is the usual choice because it’s simple, but it often comes with a quiet catch: the broker may let you place a trade right away while still holding your deposit from being withdrawn for several business days.
That’s where beginners get surprised. You might sell a stock, expect to move the cash back to your bank, and then see “funds on hold” or “withdrawal unavailable” until the transfer fully clears. Wires can move faster, but banks commonly charge for them, and some brokers charge to receive or send them.
Before you fund, open the app’s deposit screen and read the timing and fees line by line—because it sets what you can realistically buy this week.
Finding the right ticker and deciding how much to buy
Once the money shows as “available,” most people type a company name, tap the first result, and assume they’ve found the stock. That’s how you end up on a lookalike ticker, a foreign listing, or an ETF with a similar name. Slow down long enough to confirm the ticker symbol, the exchange (like NYSE or Nasdaq), and the company description on the quote page before you think about price.
Then decide size in dollars, not ego. If your app supports fractional shares, you can start with $25–$200 and still get a real fill; if it doesn’t, you’ll need enough to buy at least one full share. Also leave a small cash buffer, because price moves between the quote and the fill, and some brokers won’t let you spend every last cent.
When you’re ready, you’ll face the choice that changes your outcome most in the moment: the order type.
Market order or limit order—what you choose changes the price you get
That choice shows up as two buttons that look harmless: market or limit. A market order says “buy now,” so your broker routes it and fills you at the best available prices in that moment. In a calm, liquid stock during normal market hours, the fill is often close to the quote you saw. In a fast move, a thinly traded name, or right after a big headline, it can land meaningfully higher than expected.
A limit order flips the instruction: “buy, but only up to this price.” That protects your ceiling, which matters if you’re placing the trade outside regular hours or you’re buying something that jumps around. The cost is simple and real: you might not get filled at all. You can set a limit and watch the stock move away while your order just sits there.
If you’re buying your first small position, a limit near the current ask is a common way to avoid a surprise fill—then you can focus on what happens after the order executes.
After you buy: what you’ll see in the app (and what can go wrong)
That “what happens after the order executes” moment is when the app starts showing new labels: “filled,” “partial fill,” “average price,” and a position with a share count (or fraction) plus today’s gain/loss. You may also see “open order” for a while if your limit didn’t fully fill. Don’t assume a screenshot of the quote is your price—use the confirmation or trade history for the actual fill and any fees.
Two common surprises hit here. The first is timing: cash from a sale can show up as “unsettled,” so you might be blocked from withdrawing it right away, and frequent buy-sell moves can trigger warnings. The second is corporate actions and dividends: splits, ticker changes, or “pending dividend” lines can look like errors for a day or two while records update.
The clean habit is simple: check the fill details once, then zoom out to what owning it feels like over the next week.
Your first week of owning a stock: expectations, risks, and the one mistake to avoid
That “owning it feels like” shift usually starts with you refreshing the app more than you expected. The price will move every day, sometimes for no clear reason, and your gain/loss will swing even if the company didn’t “do” anything. Expect your first week to feel noisier than your decision was.
Watch for one risk that’s easy to miss: concentration. If you put most of your available cash into one stock, a normal 5–10% dip can turn into panic selling, especially if your deposit is still on hold. Start smaller than you think you should, keep some cash free, and set a simple rule for when you’d add—or walk away.