The raise that comes with a longer drive
The offer letter looks clean on paper, and the number that catches your eye is the raise. Then the map tab stays open a little too long. The new route is longer, the arrival time is less predictable, and there’s a quiet sense that the “extra pay” might already be spoken for. It’s not just fuel; it’s parking rules that change by building, tolls that are easy to forget, and the chance that one repair lands in the same month as a higher credit-card bill. Before anything else gets compared, the raise has to be translated into what it buys after the drive.
Start by treating the commute like a deduction that scales with distance. A longer drive often converts part of a salary bump into recurring spend: gas, tolls, paid parking, and maintenance tied to miles rather than lifestyle. Even when housing is cheaper farther out, this new line item is less stable than rent because it moves with prices, traffic patterns, and car reliability. If the raise is $400 a month after tax, but the drive reliably claims $250–$350—and occasionally $700 when something breaks—the “raise” behaves more like a variable stipend than new capacity in your budget.
Start with your expected monthly commute cost
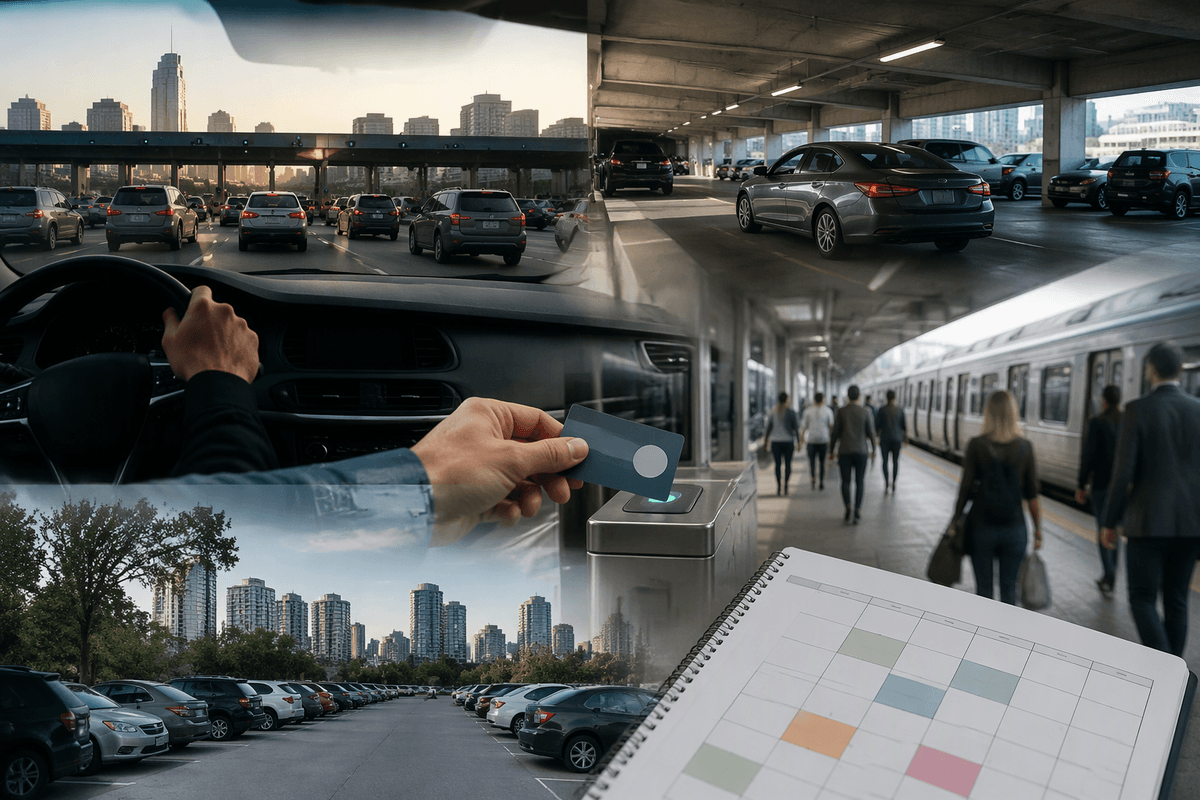
The next step is to pin down a “normal month” for the commute, even if it feels a little fake at first. Take the route you’d actually drive (or the transit you’d actually take), then convert it into counts: round-trip miles, days in the office, and the number of paid segments that don’t care what your salary is. If the schedule is hybrid, don’t default to five days; use the policy you’re likely to live with for the next year, not the best-case week you’re imagining right now.
Build the estimate from separate lines so the weak spots show. Fuel is miles ÷ mpg × local gas price; tolls and parking are “per day × days,” not occasional annoyances. Add a maintenance-and-tires line based on miles (oil, rotations, consumables), plus a small buffer for the parking ticket, dead battery, or rideshare home when the car won’t start. If you’re on transit, include passes, station parking, and the last-mile costs that show up when the timing slips.
Reality check: the first surprise bill arrives
The estimate usually survives exactly one cycle, and then a bill shows up that doesn’t fit the “normal month.” It’s often something boring: new brake pads sooner than expected, a tire that fails an inspection, a parking garage rate that quietly resets, or a toll statement that includes the days traffic pushed you onto the priced route. None of it feels catastrophic, but it lands as a lump sum, and that’s the point: commute costs don’t arrive smoothly even when the miles are consistent.
When that first surprise hits, treat it like a data point, not bad luck. Log it in the commute category and convert it into a monthly equivalent so you can compare it to rent savings without flinching. A $900 repair over a year is $75 a month; over six months, it’s $150. If the difference between “near” and “far” housing is only $200–$300 a month, one uneven invoice can erase the margin and force the budget to borrow from groceries, credit cards, or savings.
Time turns into money when your week shifts
After the first uneven bill, the next strain usually shows up in the calendar, not the checking account. The longer route starts pulling time out of places that used to absorb it: the early meeting that now requires a 6:30 departure, the gym session that turns into takeout, the midweek errands that get pushed to Saturday and turn into a more expensive “catch-up” run. Even if the commute cost line looks stable, the week re-prices itself in smaller purchases and missed routines, and it does it without asking for permission.
To make it comparable to rent, convert the time swing into something you can budget. Track the weekly delta in commute time (including parking, walking, and the bad-traffic days), then decide what it replaces: paid overtime you can’t take, a side gig shift you drop, or recurring convenience spending you adopt. If the shift is 4 extra hours a week and it reliably triggers $25 of extra food or services each workday, that’s roughly $500–$700 a month. That number isn’t “optional” once the pattern sets.
Stress-test the volatile parts before you commit
Once time and “normal month” costs are on paper, the decision starts hinging on the stuff that refuses to stay normal. Gas prices move, parking contracts change, and a car can be fine for nine months and then take $1,400 in one week. The mistake is treating those swings like edge cases when they’re really the price of depending on a longer route. Before you count the rent savings as real, run the commute budget through a couple of ugly-but-plausible months and see what it does to cash flow.
Take your baseline and add three shocks: a fuel increase (say +20%), a parking/toll increase (+10% or one extra paid day per week), and one repair event sized to your car’s age (tires, brakes, suspension—pick one). Then force it into the same month as a high-fixed-cost week: annual insurance renewal, a family trip deposit, or a medical bill. If that single month pushes you to carry a credit-card balance, the commute isn’t just more expensive—it’s riskier than the rent line you’re trying to beat.
Compare two budgets: near home vs farther rent
At this point the question stops being “can the commute fit” and turns into “does it beat the alternative.” Put two versions of the next 12 months side by side: the place closer in with higher rent, and the cheaper place farther out with the commute fully priced in. Keep the categories identical so the comparison doesn’t hide in formatting: rent, utilities, insurance, groceries, debt minimums, savings, plus a dedicated commute block that includes baseline costs and a monthly repair reserve.
Then compare on annual cash flow, not the first month. If “farther” saves $350 in rent but adds $220 in baseline commute plus a $100 reserve, the real savings is $30 before time effects. If the stress-test month forces $600 onto a card once a year, price that interest or payoff plan into the far budget. The “near” option often wins by being boring: fewer spikes, fewer timing failures, and a cleaner path to consistent savings.
Decide your breakpoint, then set guardrails
After you’ve seen both budgets survive a bad month on paper, the breakpoint usually shows up as a number, not a feeling: the maximum annual “commute premium” you can tolerate before it starts stealing from savings or pushing balances. A clean way to set it is to require the far option to beat the near option by a fixed margin after reserves—say $1,500–$3,000 per year—so one repair season doesn’t erase the win.
Then add guardrails that make the decision durable. Cap commute spending at a percentage of take-home pay, pre-fund a repair reserve with automatic transfers, and pick an exit trigger (for example: two credit-card months in a year, or a commute block that runs 25% over plan for 90 days). If you can’t name the trigger, you’re not buying savings—you’re renting risk.